Refund vs chargeback: what's the difference — and why refunding is almost always cheaper
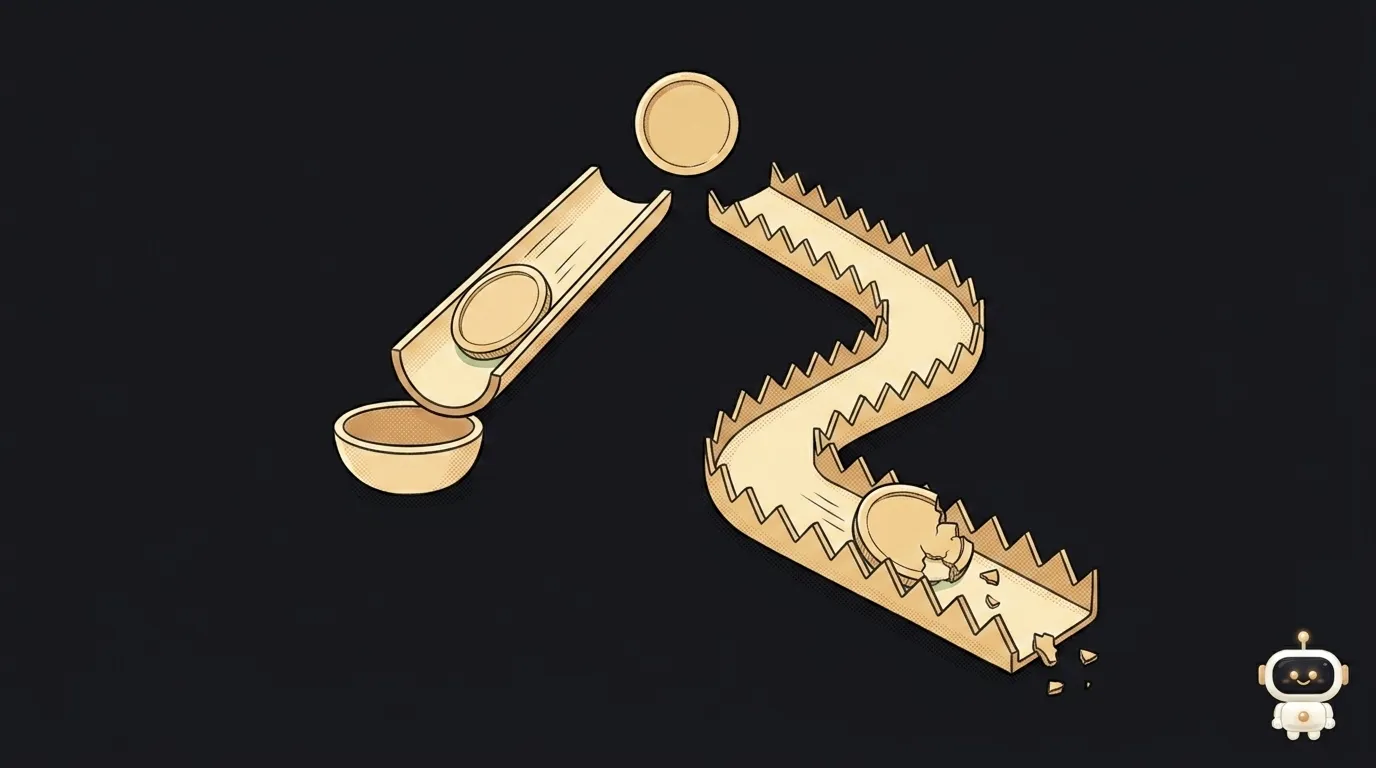
A customer is unhappy and wants their money back. Something fair rises up inside: "but I delivered, the product works, let them prove otherwise".
The thing to count here isn't fairness — it's money. And the arithmetic is surprising: arguing costs more than paying up.
The difference in one sentence
A refund is you sending the money back. A chargeback is the customer's bank taking it from you, and you finding out afterwards.
For the customer the outcome is nearly identical: money returned. For you, the two are worlds apart.
Compared, criterion by criterion
Who presses the button. Refund: you, from your dashboard, one click. Chargeback: the customer, through their bank, without you.
Who decides. A refund is decided the moment you issue it. A chargeback is decided by the customer's bank, and your payment provider has no influence — it only forwards your evidence.
How long it takes. Refund: seconds on your side, a few days to reach the card. Chargeback: 7–21 days for your response, 60–75 days for the bank's decision, 2–3 months end to end.
What it costs. A refund carries no dispute penalty. A chargeback carries a non-refundable fee just for existing, plus a separate fee if you fight it (that one comes back if you win).
Whether it counts against you. Refunds don't count toward your dispute rate. Disputes count — all of them, including the ones you win — and the "too many" threshold starts around 0.75%.
Whether you can change your mind. A refund can't be undone; the money's gone. A chargeback can't be settled amicably either: while it's open you can't issue a normal refund on that payment, and if the customer backs down you still have to respond with evidence.
The mechanics of the dispute itself are in what is a chargeback.
Which one to choose
No fence-sitting.
Refund without hesitating when:
- the amount is small. Stripe has a direct recommendation for suspicious payments: refunding makes sense roughly up to the size of your dispute fee, and is barely worth it once a payment exceeds that fee by more than a third. Below that line, a dispute loses money regardless of outcome;
- the customer simply changed their mind and your product is digital, so nothing physical was lost;
- you can see they misunderstood what they were buying;
- an early fraud warning arrived and the payment wasn't confirmed via 3-D Secure. By Stripe's estimate, 80% of those warnings become disputes if you do nothing.
Fight it when:
- the amount is meaningfully larger than the countering fee;
- you have real evidence: receipt, login logs, delivery confirmation, messages where they thank you for the product;
- you see a systematic abuse pattern and don't want to become an easy target.
Accept immediately when you have no evidence. That's not defeat, it's saving two months on a case you'd lose anyway.
The window where the choice is still yours
Between "customer is unhappy" and "chargeback arrived" there's often an in-between stage: the bank asking for information. Amex and Discover use it most.
That window is the valuable one. At this stage the case can close without a dispute fee in two ways: a clear answer to the bank's question, or a full refund. Ignoring the request is the worst move — silence reads as agreement, and the case escalates into a nearly unwinnable chargeback.
Two details that break naive plans:
- a partial refund doesn't save you. You refunded half, you agreed on it — and they disputed the whole amount anyway. That's allowed, and it happens regularly;
- a fast refund doesn't erase a fraud report. It's already in the network. The one exception is reversing the transaction entirely within the first couple of hours after capture.
What if they demand a refund on a product that has none?
Your refund policy protects you only if the customer saw it before paying and it doesn't conflict with local law. A line buried in your footer won't hold up against a bank. Simple test: if you can't show the policy in one dated screenshot, assume you don't have one.
Do refunds hurt my standing with the payment provider?
An abnormally high refund rate does draw attention — it hints at product problems. But between "a few too many refunds" and "a few too many disputes", the first wins every time: disputes threaten your ability to accept cards at all.
How do I make this choice less often?
A readable name on the card statement, a receipt email right after checkout, an obvious cancel button, and replies to email within a day. Boring — and it removes most disputes before they exist. If payments aren't set up yet, start with how to take your first payment.
The AI Architect 2027 course: step by step from computer basics to your own app and first customers. 543 short lessons on your phone.
Read next

Why SSH still asks for a password when your key is set up — 3 causes

How to set up ~/.ssh/config — short server names instead of long commands

Why does SSH disconnect on its own (Broken pipe) — three causes and how to fix them

How to read command help (--help and man) — and find your version's flags in a minute

Why Ctrl+C doesn't stop a program — and how one except line causes it
